Your signature can commit you to a payment deadline before your bank releases a single ringgit. When reviewing a sale and purchase agreement in Malaysia, focus on the clauses controlling your money, ownership and handover.
A property SPA in Malaysia can differ depending on the transaction and applicable law. Have your own SPA lawyer review it before signing, starting with the obligations that could cost you most.
Quick Answer
Before signing, check the property details, title, purchase price, deposit, financing conditions, payment deadlines, vacant possession, defects and termination rights. Confirm who pays each cost and what happens if either party defaults.
Developer purchases may use prescribed housing agreements, while subsale terms are usually negotiated. Your lawyer should explain which rules apply and put enforceable promises into the appropriate documents.
Key Takeaways
- Confirm the exact property, seller, title status and included fixtures.
- Don’t assume loan rejection or personal hardship guarantees a deposit refund.
- Check when payment deadlines begin and whether extensions attract interest.
- Read handover, late-delivery and defect clauses together.
- Separate stamp duty, legal fees and disbursements when budgeting.
Which Sale and Purchase Agreement Applies?
Developer purchases: Schedule G and H
For purchases covered by the federal housing development framework, Schedule G commonly applies to land and a building. Schedule H commonly applies to a unit in a subdivided building, such as a condominium.
These prescribed forms set out buyer protections and developer obligations. However, a project’s marketing name or land classification alone doesn’t settle whether those protections apply.
Ask your lawyer to confirm the applicable scheme. Sabah and Sarawak have separate housing laws, so federal forms aren’t a universal rule across Malaysia.
Subsale purchases: review the negotiated terms
When you buy an existing home from its owner, the SPA usually contains negotiated terms. Completion periods, extensions, included furniture and remedies can differ between agreements.
You shouldn’t assume a sub-sale property comes with the same defect protection as a qualifying developer purchase. SureLah’s comparison of subsale and new launch homes helps you assess the practical differences before committing.
Check the Property, Title and Written Promises
Match the agreement to the home you’re buying
Check the seller’s name, unit number, address, land or parcel particulars, floor area and parking entitlement. For a developer purchase, also examine the attached plans and specifications.
If the deal includes air conditioners, kitchen cabinets or furniture, identify them in writing. A showroom display or WhatsApp promise may not become an enforceable contractual obligation automatically.
Ask how the agreement handles differences in area or specifications. Don’t accept a broad verbal assurance that everything will match the show unit.
Understand title restrictions and transfer requirements
Your lawyer should search the title and check ownership, charges, caveats and restrictions. For leasehold property, confirm the remaining tenure and any necessary consent.
If an individual or strata title hasn’t been issued, ask how your interest will be transferred and documented. The process may involve an assignment rather than an immediate registered transfer.
Review freehold and leasehold ownership differences alongside the actual title findings. Tenure alone won’t reveal every restriction affecting your purchase.
Review Deposits, Financing and Default Clauses
Know where your deposit goes
Check the deposit amount, payment recipient and whether a lawyer holds the money as stakeholder. Also confirm when the stakeholder can release it.
A subsale earnest deposit often forms part of the overall deposit. Your offer document and SPA should clearly account for money already paid.
For an HDA-regulated developer purchase, ask your lawyer whether any requested pre-SPA booking fee is lawful. Don’t assume a payment is acceptable because the sales team calls it a reservation fee.
Read the exit conditions before committing
Check whether the agreement provides relief if financing fails, and what proof or notice you must supply. Loan rejection doesn’t automatically cancel every SPA or trigger a full refund.
Also distinguish rejection from insufficient financing. If your bank lends less than expected, you may need to fund the shortfall yourself.
A financing condition may require written rejection evidence within a deadline. Missing that deadline can affect your rights even when the bank declines your application.
Read the default notice, cure period, forfeiture and termination provisions together. Personal hardship doesn’t create a universal right to walk away without financial consequences.
Pin Down Payment and Completion Deadlines
Identify what starts the clock
For subsale transactions, check how the contract completion date is calculated, for example, from signing, receipt of consent or another defined event. A familiar “three months plus one month” arrangement is a contractual practice, not a universal statutory deadline.
Ask whether an extension is automatic or needs approval, and how late interest is calculated. Also check how the SPA treats delays involving the seller’s bank, redemption documents or missing paperwork.
Your bank loan approval isn’t the same as loan disbursement. Both legal documentation and bank conditions can affect release.
Check payment triggers and outstanding charges
For a developer purchase, review the progress-payment schedule and the certification required before each instalment becomes due. Confirm when you must pay any difference between the loan and purchase price.
For subsale, clarify responsibility for assessment, quit rent, maintenance charges and utilities. The agreement should explain how the parties divide these costs at completion or handover.
Also budget for condo costs beyond the purchase price, including maintenance and sinking fund contributions. Your purchase budget must cover ownership after you receive the keys.
Check Property Handover, Late Delivery and Defects
Define vacant possession and late-delivery rights
For commonly used prescribed developer agreements, reported delivery periods are 24 months under Schedule G and 36 months under Schedule H. Have your lawyer verify the applicable form, deadline and any lawful variation.
Check what makes vacant possession valid, including required certification, notices and service arrangements. An invitation to collect the keys doesn’t settle every contractual handover requirement.
The legal guidance on late-delivery damages explains liquidated ascertained damages, commonly called LAD. Relevant prescribed agreements commonly calculate late-delivery damages at 10% per annum of the purchase price. Your lawyer should verify the correct period and calculation.
Record defects and follow the notice procedure
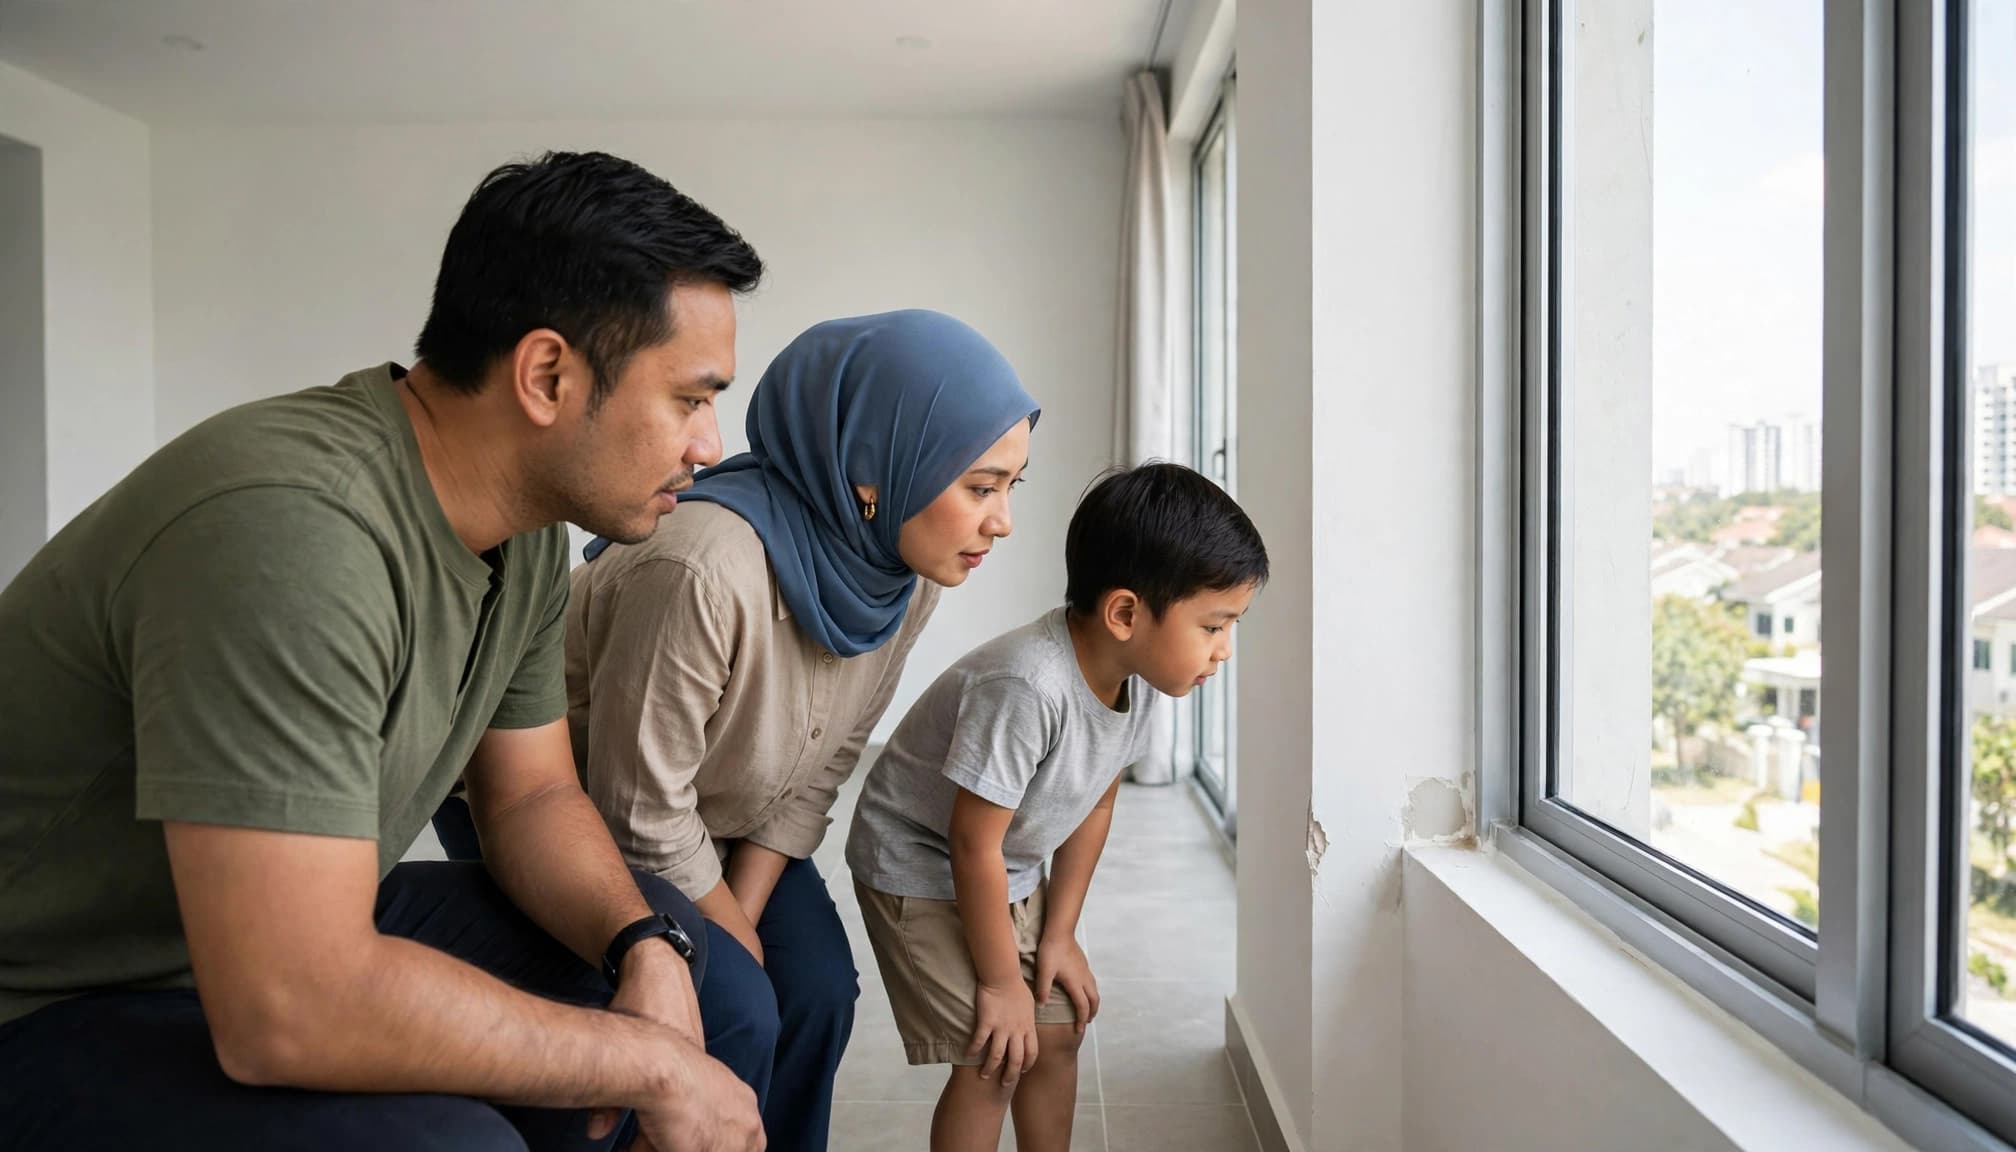
Check your agreement’s defect liability period rather than assuming one duration applies to every property. Review the notice method, repair deadline and procedure if repairs remain incomplete.
Photograph defects and submit a dated written list. Keep proof of delivery, inspection records and repair correspondence.
For a subsale property sold “as is”, inspect carefully before signing and document agreed repairs. If a dispute remains unresolved, ask your lawyer whether a housing tribunal claim or court action is available, and about filing deadlines.
Separate Stamp Duty From Legal Fees
Calculate transfer and loan duty separately
The SPA records the deal. The Memorandum of Transfer, commonly Form 14A where applicable, is the instrument for registered ownership transfer. Stamp duty is a tax on the relevant instrument.
The standard stamp-duty breakdown describes these progressive transfer rates, subject to applicable exceptions.
| Portion of assessed property value | Rate |
|---|---|
| First RM100,000 | 1% |
| Next RM400,000 | 2% |
| Next RM500,000 | 3% |
| Above RM1 million | 4% |
For a RM600,000 assessment, transfer duty totals RM12,000, rather than 3% of the entire value. Assessment generally uses the purchase price or market value, whichever is higher.
A RM540,000 housing loan typically attracts RM2,700 duty at 0.5%, before exemptions. Together, these duties total RM14,700, excluding legal fees.
Verify exemptions and request itemised fees
A qualifying Malaysian citizen who is a first-time home buyer may qualify for full transfer and loan stamp-duty exemptions. The first residential home must be priced at RM500,000 or less. Current relief covers qualifying SPAs dated through 31 December 2027, subject to conditions.
Ask your lawyer to verify eligibility against LHDN’s stamp-duty exemption orders. Prior ownership, including some inherited or gifted interests, can affect eligibility.
For Peninsular Malaysian conveyancing, fees fall under the Solicitors’ Remuneration Order 2023, effective since 15 July 2023. Request separate figures for legal fees, disbursements, applicable SST and stamp duty. A stamp-duty exemption doesn’t waive lawyer fees.
Choose a Lawyer Who Explains Your Risks
Choose a Malaysian conveyancing lawyer familiar with your transaction type and location. Ask who handles your file, how you’ll receive updates and whether the quotation covers both purchase and loan agreement work.
If the developer offers “free legal fees”, confirm whose lawyer the firm is and what the offer excludes. A lawyer preparing documents doesn’t necessarily represent your interests.
Before signing your property SPA in Malaysia, request a written explanation of unusual clauses and outstanding approvals. Keep the final agreement, payment receipts and correspondence together. Confirm bank-account changes through a trusted, independently verified contact before transferring money.
FAQs About Malaysian Property SPAs
Can I get my deposit back if my loan is rejected?
It depends on the applicable rules and your documents. Check the financing clause, required evidence and notice deadline. Have your lawyer review both the booking or offer document and the SPA before claiming a refund.
Can I terminate because of family hardship?
You can seek a negotiated release, but hardship doesn’t automatically entitle you to a refund. Your SPA may permit forfeiture or other remedies. Obtain legal advice before stopping payments, because missed instalments can create a further breach of contract.
Is signing the SPA enough to become the registered owner?
Signing creates contractual rights and obligations, but registered ownership requires the appropriate transfer and registration process. Where title isn’t available, different documentation may apply. Ask your lawyer what remains outstanding and how your interest is protected meanwhile.
Before You Sign, Resolve the Expensive Uncertainties
A property purchase becomes easier to assess when you understand what triggers payment and what happens if something goes wrong. Clear title details and written promises matter as much as the price.
Use this guide as general educational information, not legal advice. Have your own Malaysian conveyancing lawyer review the applicable rules and your individual SPA before you commit.